 by
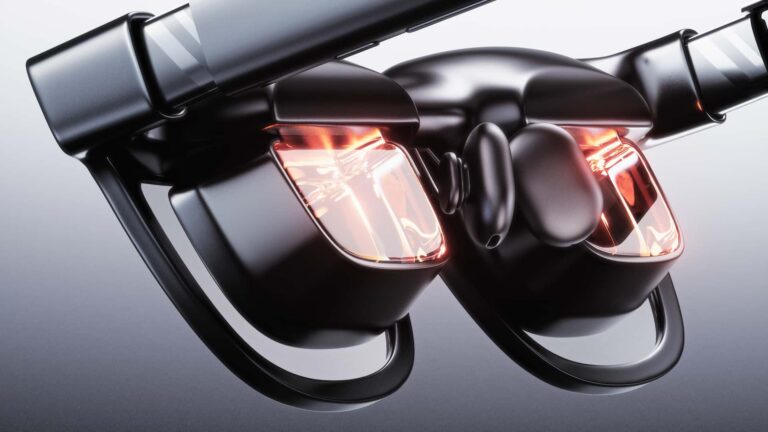
Though spatial computing and all its subsegments continue to hold great potential, they also face headwinds. Factors holding them back include challenged technological advancement and cultural adoption. However, bright spots include the rise of AI- powered smart glasses.
For example, as seen in Meta’s earnings, smart glasses have offset declines in other subsegments, such as consumer VR. Altogether, it’s a mixed story with both positive and negative drivers. The good news is that the positives will mostly outweigh the negatives in the near term.
To wrap some numbers around these claims, spatial revenue is projected to grow from $28.2 billion in 2025 to $59.7 billion in 2030. That’s steep growth, driven by a projected inflection next year as new smart glasses blitz the market from Apple, Meta, Google (AndroidXR), and others.
What else is driving spatial revenues, and what are strategic implications? These questions are tackled in the latest spatial revenue forecast from our research arm, ARtillery Intelligence. This Behind the Numbers series excerpts those insights, continuing below with top revenue drivers.
Follow the Money
As noted, global spatial computing revenue is projected to grow from $28.2 billion in 2025 to $59.7 billion in 2030. This represents a 16.2 percent compound annual growth rate (CAGR), which is fairly steep. So what’s driving XR revenues? Some subsets are doing better than others.
Specifically, we subdivide revenue totals into three categories: mobile AR, headworn AR, and VR. Those top-level segments then branch into several subdivisions, such as device tiers, as well as consumer and enterprise spending. Altogether, it’s a matrix of revenue categories.
Among these, VR leads in revenue ($13.75 billion last year) as it’s more established than the other segments. However, it’s not where the momentum lies (more on that in a bit). And though it leads in revenue, it doesn’t lead in units sold – a difference that comes down to price points.
VR also leads in revenue because it has a large revenue stream from software (apps, experiences, and enterprise software). Though smart glasses are a momentous category, which we’ll explore next, there isn’t yet an ecosystem of apps and experiences – at least paid ones.
AR’s Endgame
On to headworn AR, it likewise includes subdivisions, including full spatial experiences like Snap Specs, flat AR, such as video display glasses, and non-display AI glasses. The latter is close to dethroning VR’s position as the revenue leader, and it already leads in unit sales.
Starting with Ray-Ban Meta Smartglasses (RMS), the high-growth device sidesteps AR displays in favor of AI-driven augmentation, delivered audibly. Meanwhile, Meta pursues the advanced end of the experiential spectrum with Orion – a prototype that teases visual AR’s endgame.
These two endpoints – today’s attainable reality and tomorrow’s AR moonshot – are bridged by Meta Ray-Ban Display Glasses (MRD*). These offer flat AR for messaging, notifications, and other utilities. This is a category that’s projected to grow in 2027 and 2028 as several players enter.
Altogether, these various classifications of the spatial spectrum represent a key trend: the diversification of XR into purpose-built devices. This divergence of form factors will define the next few years of XR evolution, branching into form factors that map to specific use cases.
Consumer Traction
Moving on to the final top-level XR hardware category, mobile AR has been an early leader as it taps into a massive global installed base of smartphones. This is what we call zero-cost hardware because it utilizes the device that’s already in your pocket, thus lowering adoption barriers.
To wrap some numbers around that, mobile AR revenues were estimated to reach U.S. $8.9 billion last year (2025). Again, this piggybacks on 3 billion+ global smartphones, but to clarify, hardware spending (all those smartphones) isn’t included in the above revenue total.
So where is that $8.9 billion being spent? Mobile AR’s top revenue categories include enterprise productivity and AR marketing & commerce. Notably, both of these revenue categories claim enterprises as buyers, though the latter have consumer-based endpoints (B2B2C).
That’s the thing with mobile AR. Though it has ample consumer traction – owing to those lowered adoption barriers – that doesn’t equate to revenue. To date, most consumer AR is brand-sponsored rather than user-purchased, though Snap’s Lens+ is starting to change that.
We’ll pause there and circle back in the next Behind the Numbers installment with more numbers & narratives. Meanwhile, check out the full report.